Pros and cons of a TSP “In-Plan Conversion” versus rolling out to a Roth IRA?
Recently, the retirement landscape for federal employees has changed dramatically. The introduction of In-Plan Roth Conversions within the TSP means you no longer have to move your money to an outside bank just to get it into a Roth account.
However, "easier" isn't always "better." Here is the breakdown of how the new in-plan option stacks up against the traditional "roll-out" strategy.
The "In-Plan" Advantage (The New 2026 Way)
If you love the simplicity and safety of the TSP, this is your best bet.
-
Frequency: You can perform up to 26 conversions per year (once per pay period). This is perfect for "dollar-cost averaging" your tax bill—converting a small amount every two weeks to avoid jumping into a higher tax bracket.
-
The "Leave Behind" Rule: You must keep at least $500 in your traditional balance to keep that specific "source" account open.
-
No RMDs: Starting in 2024/2025, Roth TSP balances (including converted ones) are not subject to RMDs during your lifetime, matching the biggest benefit of Roth IRAs.
The "Roll-Out" Advantage (The Traditional Way)
If you want total control over your money, moving it to a private IRA (Fidelity, Vanguard, etc.) still has perks.
-
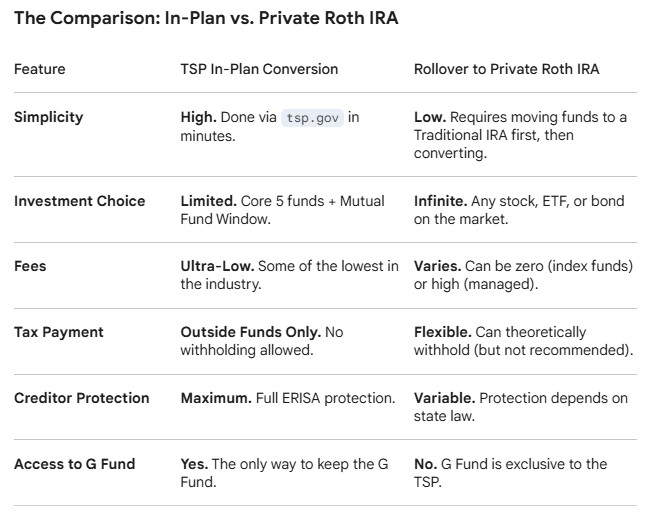
Asset Specificity: In the TSP, if you convert $10,000, it pulls pro-rata from all your funds (C, S, I, etc.). In a private IRA, you can choose to convert only your worst-performing asset or only your high-growth stock.
-
No $500 Minimums: You can drain a traditional IRA to zero without "closing" the account or dealing with minimum balance rules.
-
Better Heir Options: While the TSP is great for you, private IRAs often have more flexible "stretch" options or beneficiary tools for your children.
Critical 2026 Update: The "Pro-Rata" Trap
One thing the new TSP conversion tool does not let you do is "cherry-pick" your tax-exempt money.
Example: if you have $10,000 in "Tax-Exempt" combat zone pay and $90,000 in "Traditional" pay, any conversion you do will be 90% taxable. You cannot choose to convert only the tax-exempt portion first.
Which one should you choose?
-
Stay in the TSP if: You want the G Fund, you value ERISA-level asset protection, and you want to automate your conversions every pay period.
-
Roll out to an IRA if: You want to invest in individual stocks, you have a complex estate plan, or you want to pick specific assets to convert.