Understanding Credit Reporting

Historically low interest rates present a welcome opportunity for many homeowners to improve their financial situation by refinancing their mortgage.  But, like everything else in the world of finance, there are no free lunches.  To take advantage of these lower rates, homeowners must leap the FICO hurdle.

To qualify for the best loans at the lowest rates, borrowers must qualify financially and are scored by lenders using a computerized model for evaluating credit risk, developed by Fair, Isaac, and Company, known as the FICO score.

Mortgage lenders are in the business of making money by lending it and being repaid on time.  They gauge the risks associated with making that loan on a number of factors, not the least of which is the likelihood of timely repayment.

The FICO scoring system compares borrower’s credit capabilities to those of similar borrowers all over the country.  A borrower’s credit history gives a strong indication of integrity, attitude, and discipline as well as a measure of their capability to pay bills on time.

Three major credit reporting agencies gather credit information:  Experian, Equifax, and Transunion.  The firms act independently of each other and use different methods for gathering information, hence the reports of each may differ. 

The reporting agencies issue several different types of reports.  A Consumer Report is the basic consumer report issued when an individual orders his own credit report.  The Merchant Report is more complete and contains the full FICO scores.

Lenders view these scores as just one of several criteria for evaluating the ability of a borrower to pay back a loan.  The scores, ranging from 0 to 850, are numbers that tell lenders how likely an individual is to repay a loan, or make credit payments on time.  The higher the score, the better the credit risk.  Scores of 700+ make A credit grades, 640+ for a B grade, and below 579 fail.

According to mortgage broker Ron Goerss of Partners Mortgage, the most important factors to mortgage lenders are mortgage history, derogatory credit history, liens or judgments, length of credit history, depth of credit history, proportion of debt to credit balances, and the amount of available credit.
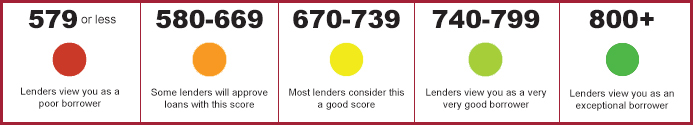
FICO Score, How To Raise my credit Score

A borrower can improve his FICO score over time by paying bills—especially mortgage payments—on time.  Late payments cost points.  To get the best scores, one should accumulate at least 36 months of a timely payment history.  Generally speaking, a borrower will have an excellent credit score with four major accounts ($1,500 credit limits or higher) all with 36 months of spotless payment history, and all usually maintaining balances that are at or below 60% of available credit limits.

Despite paying bills on time, it is still possible to have a lower credit score.  Too many open accounts with higher balances will pull the score down.  Too many inquiries hurt the score.  Too many monthly obligations weaken the score.

Finally, the real negatives are late mortgage payments, collection history, charge-offs, repossessions, and bankruptcy.  While all of those can be worked around, most lenders will refuse a conventional loan to someone with foreclosure history on their report.

It’s a good idea to periodically review your FICO score.  Erroneous information may be reported, and if you know ahead of time, you can write a letter to the credit-reporting agency and request a correction.  For more information on FICO scoring and obtaining your FICO scores: www.creditline.com and www.creditreporting.com.
How Will Rising Healthcare Costs Affect Your Retirement?

How financial advisors provide value to those saving for retirement

Important information for people with retirement plans

We all know it is inevitable. It’s no secret healthcare costs will be going up. For years, medical expenses have been steadily increasing.  In 2007, medical expenses rose almost 12 percent. However, the rate of increase slowed to 6 percent during the past five years and that trend is expected to continue for the foreseeable future, according to a June 2018 report from PwC. While single-digit increases can be considered an improvement, ever-rising costs are a concern for those who have to foot the bill, today and in the future.1

Medical expenses are often the “elephant in the room” in a retirement plan. It’s the expense people prefer not to consider because, if they do, they’ll need to save significantly more money.

How much should you save for healthcare in retirement?

According to the Fidelity Retiree Health Care Cost Estimate, the average 65-year-old couple that retired in 2018 should have had about $280,000 set aside for medical expenses in retirement, excluding long-term care. The estimate assumes the couple does not have employer-provided retiree healthcare coverage, and does qualify for Medicare.2

Fidelity anticipates retirees’ healthcare savings may be spent like this:2, 3

  • 20 percent for prescription drugs (generic, branded, and specialty)
  • 35 percent for Medicare Part B (medical insurance) and Medicare Part D (prescription insurance) premiums
  • 45 percent for additional medical expenses such as deductibles, copayments, and supplemental insurance for doctor and hospital visits

Strategies for managing retirement healthcare costs
Whether you plan to retire in five, 10, or 20 years, there are a few things you can do to better prepare for healthcare in retirement:

1. Do the math. Fidelity’s estimate is an average. Your healthcare situation is unique, so it is a good idea to create a more personalized estimate, one that includes the cost of various premiums and insurance costs, as well as prescription medicines.4     

2. Get the skinny on discounts. No matter how old you are, your doctor and your pharmacist can provide valuable suggestions about how to reduce prescription drug costs. Don’t hesitate to ask about coupons or discounts that could lower your costs. Pharmaceutical companies may have coupons available through their websites. Also, investigate other options such as substituting a generic drug, using a mail-order prescription service, or filling a 90-day supply instead of a 30-day option. Even small savings can add up over time.5, 6     

3. Open a Health Savings Account (HSA). Your employer’s high-deductible health plan (HDHP) comes with a useful option – a health savings account (HSA). You can save for current and future medical expenses in an HSA, and they confer a triple tax advantage

  • HSAs are tax-deductible
  • Any interest or earnings grow tax-free
  • Distributions are tax-free when taken for qualifying medical costs

If you don’t spend the money in your HSA, you can roll it over to the next year. Also, the account is yours, even if you change employers. As a result, HSAs are a great way to save for healthcare costs in retirement.7

  1. Take Social Security at 70. Since 2011, on average, people in the United States retire at age 61, according to a Gallup Poll. That’s a year before they can start collecting Social Security. If retirees choose to begin receiving Social Security benefits at age 62, they will receive 70 percent of the benefit they would have received at ‘full’ retirement age. On the other hand, if they postpone taking benefits until age 70, they’ll receive a higher monthly payment. The amount of the payment will be determined by an individual’s age and year of birth, as well as the number of months benefits were delayed.8, 9, 10
  2. Make healthy choices. While it’s impossible to predict what the future will hold, forming healthy habits today could support a healthier life ahead. You know the drill: eat well, sleep well, exercise, socialize, and so on. Being more health conscious today could mean fewer doctor visits, hospital stays, health specialists, and prescriptions in the future.11
  • Save, save, save. The most obvious way to prepare for future healthcare costs is to save as much as you can today. If you can, maximize contributions to your employer-sponsored retirement plan, HSA, and Traditional and Roth IRA accounts. For many people, saving more is not a hardship. It’s a choice. The decisions you make today will affect how you live in the future.

Healthcare costs are likely to be a significant part of your retirement budget. If you haven’t already factored these costs into your retirement plan, you may want to consider it. The sooner you prepare, the better off you will be.

Please contact us if you want to discuss your options. We’re happy to help.

Digital Assets and Baby Boomers

How many password-protected accounts do you have?
Whether you keep them locked in the depths of your memory, use a password manager, or have a written record of your passwords (which is certainly not recommended), take a quick count. You are most likely to find you have some or all of these types of accounts:

  • Email accounts
  • Social media accounts
  • Online storage accounts
  • A domain name
  • Online bank accounts
  • Online brokerage accounts
  • A website or blog
  • Online shopping accounts
  • Online bill paying
  • Photo and video sharing accounts
  • Gaming accounts
  • Materials and coding that are copyrighted

These are all digital assets. They are part of your virtual life, as is any digital property you own, such as computers, external drives, storage devices, smart phones, digital cameras, e-readers, and other devices.

Digital assets should be part of your estate plan
Unless you live off the grid, it’s likely your digital life will outlive you and become a part of your legacy. Your digital assets may have significant financial or personal value for your heirs. Consequently, you should give some thought to how these assets should be managed after your death.1

The catch is digital estate planning can be tricky. Many digital accounts and assets cannot be transferred to a new owner because they are not your property. Assets that fall into this category are subject to contracts and licensing agreements established with a service provider.1

For example, if you’ve spent significant sums accumulating a virtual music library, you may not be able to pass it on through a will or another estate planning tool because you do not own the digital music files, according to Nolo.com. This may also be true with other types of accounts.1

“Social network accounts, domain name registrations, email accounts, and most other types of online accounts are ‘yours’ by license only. When you die, the contract is over and the business that administers the account controls what happens to it,” explained Betsy Simmons Hannibal on Nolo.com.1

This doesn’t mean you have no control over what happens to these accounts. Your estate can leave instructions about account management and should provide a complete record for your executor. Jeffrey Salas offered an opinion about best practices on LegalZoom.com. He recommended:2

  1. Checking the account providers’ Terms of Service/Terms of Use. Work with your estate planning attorney and the digital executor you’ve appointed to review requirements for different types of accounts. For example:
  • Leave usernames and passwords for any online financial accounts – banking, utilities, brokerage, mortgage, retirement plan, life insurance, tax preparation, or others – to the executor as they will need this information to pay bills, close accounts, and administer your estate.1
  • Social media companies have diverse policies regarding the management of digital assets upon the death of the user. Some delete or deactivate accounts after being notified of a death. Others put accounts into ‘memorial’ status.1
  • In general, companies will not know about the death until they’re notified. As a result, a digital executor who is armed with passwords may be able to access your account to post final updates, delete items (per estate instructions), or delete/deactivate accounts.1
  • Email accounts, online communities, and blog management may also be guided by provider agreements. However, your executor may be allowed to notify friends or followers of your death and then delete, print, or archive your communications.1
  • Digital photos that are stored online may be passed on through a will or another estate planning tool.1
  • If you have one or more websites, domain names may have value and they may be transferrable.1
  • If you have an online store, you may want to leave instructions about what should happen to the store, the items for sale, and any income or profits that may continue to arrive.

    2. Add language regarding digital assets to your will and/or trust. Currently, there is no uniform federal law to guide the management of digital assets.2 At the start of 2017, Kiplinger reported, “Federal law regulating access to digital property does not yet exist. At this time, 29 states have established legislation or laws to protect digital assets and to provide a deceased person’s family procedures and rights to manage those accounts and assets after death.”3  Regardless, it can still be a good idea to include language that specifies your wishes for the treatment of each of your digital accounts.2


    3. Check the law in your state. Talk with your attorney or advisor about whether any laws your state has that apply to digital assets, and make sure your estate plan is consistent with these laws.2

While estate and inheritance laws are behind the curve when it comes to digital assets, it is important to inventory your digital assets and decide how they should be managed upon your death. If you would like additional information about estate planning, please give us a call.


Sources:
1 https://www.nolo.com/legal-encyclopedia/a-plan-your-digital-legacy.html
2 https://www.legalzoom.com/articles/what-happens-to-your-digital-assets-when-you-die
3 https://www.kiplinger.com/article/retirement/T021-C032-S014-put-digital-assets-in-your-estate-plan.html

Are You Ready to Retire?

In the United States, we have a potential crisis on the horizon.  The majority of Americans are not financially prepared for their retirement.

Some future retirees are completely unprepared. The Employee Benefits Research Institute (EBRI)’s 2017 Retirement Confidence Survey found almost half (47 percent) of workers have less than $25,000 in personal investments and savings, and about one-quarter has less than $1,000.1

But many are better prepared. Slightly more than half of survey participants were actively saving for retirement. However, not many had taken other steps to prepare such as:1

  • Gauging monthly retirement income needs (38 percent)
  • Preparing a formal, written financial plan for retirement (11 percent)
  • Estimating Social Security benefits at a planned retirement age (38 percent)
  • Thinking about moving or downsizing (38 percent)
  • Determining expenses in retirement (34 percent)
  • Talking with a financial advisor about retirement planning (23 percent)

It is relatively unsurprising to learn people who are most confident about retiring have spoken with a professional financial advisor about retirement planning.1

While working with financial advisors may improve retirement outcomes, saving is critical for anyone who wants to retire from working full-time. In fact, the majority of workers and retirees participating in a recent Wells Fargo survey wish they had begun saving for retirement sooner than they did.2

Factoring in the healthcare variable
No matter when individuals begin to save or how much they’re setting aside, even sound retirement plans can be disrupted by rising healthcare costs and catastrophic illness. There is evidence Americans are concerned about healthcare issues. However, few have factored healthcare expenses into their retirement plans.2

According to a recent Wells Fargo survey, “Nearly half of workers (45 percent) have not actively considered health care expenses for retirement planning, and even among workers age 60+ nearly a quarter (23 percent) have failed to take healthcare expenses into account.”2

It’s daunting to consider health expenses have increased faster than inflation in recent years. In addition, patients are being asked to pay a larger share of the expense. U.S. government figures show spending on healthcare rose by 5.8 percent in 2015. From 2016 through 2025, spending was expected to grow by 5.6 percent a year, on average.3

Retirees feel the effects of higher healthcare costs more than younger Americans do. The Centers for Medicare and Medicaid Services reported, “Per person, personal healthcare spending for the 65 and older population was $18,988 in 2012, over 5 times higher than spending per child ($3,552) and approximately 3 times the spending per working-age person ($6,632).”3

So, how much is healthcare likely to cost during retirement? An expert cited by Morgan Stanley suggested the average retired couple “will spend somewhere between $259,000 and $395,000 over the course of their retirement, depending on their lifespan and health conditions.”4

The news may shock people who believe they’ll need less than $500,000 to retire comfortably (about one-third of those participating in the EBRI RCS).1 Even for people who plan to save more, adding healthcare expenses to retirement calculations may significantly increase savings goals.

Moving toward a comfortable retirement
If thinking about retirement makes you a bit queasy, it’s likely you haven’t prepared as well as you should. The good news is developing and implementing a retirement plan is fairly straightforward. Here are a few steps that can help boost retirement confidence:

  • Create a retirement budget. A retirement budget is no different than a current household budget. Write down (item by item, line by line) how much you expect to spend in retirement. Obviously these estimates will become more accurate as retirement nears.
  • Save for retirement. For many people, a successful retirement strategy means saving at least 15 percent of their income.5 Those who have the good fortune to participate in an employer’s retirement plan may benefit from employer-matching contributions. If you don’t have a retirement plan at work, open an IRA and set-up automatic contributions each pay period.
  • Choose an asset allocation strategy. Asset allocation is dividing your savings among different investments, such as stocks, bonds, and other options. The way people invest their savings is often determined by their age, risk tolerance, and retirement goals.5
  • Prepare for long-term care. Three-of-four retirees will need extended long-term care. If you haven’t planned for it, the cost can really put a dent in your retirement savings. Medicare Part A covers skilled nursing care in a skilled nursing facility for a specific period of time after hospitalization. It does not pay for custodial care for Alzheimer’s or other cognitive illnesses. Consequently, it may be wise to purchase long-term care insurance or add a long-term care rider to a life insurance policy.6
  • Review your plan every year. Retirement planning is not a static activity. Retirement goals may change significantly over a lifetime. As a result, it’s important to review retirement plans often and make any changes needed.

Will you be able to retire comfortably?  It’s a complicated question.  The answer can be equally complicated. If you would like help figuring it out, or want to review your current plan, contact us for a no-obligation consultation.

A Financial Advisor’s Blueprint To Making Solid Financial Decisions

Decide What Is Most Important To You

A common mistake people make is to give up what they want most for what they only want right now. Pick which goals in your life are most important to you, and make achieving those goals your utmost priority. Then...

Always Ask Yourself, "Will This Decision Bring Me Closer To My Goals, Or Take Me Further Away?"

People commonly prioritize the short-term over the long-term. But a great way to determine if the decision is a good one is to ask yourself if you are mortgaging your future to pay for your present.

Don't Rush. Take Your Time And Study Your Options

Financial Decisions rarely need to be made in a hurry. In fact, fast decisions tend to be poor decisions!  Get all the facts and learn your option, so that your decision is at least an informed one.

That Said, Focus On Making "Good" Decisions Over "Perfect" Decisions.

Volaire once said, "perfect is the enemy of the good."  When making a financial decision, don'[t stress so much over whether your decision is perfect that you end up paralyzing yourself and missing out on opportunities. A lot of small, good decisions tend to weigh more than one perfect decision.

Ask Questions!

The most important thing you can do to make good financial decisions is to ask questions first. Talk to qualified experts. Chat with people who've been in the same situation as you. As the saying goes, "He who asks a question is confused for a minute. He who does not is confused forever."

We are here to help you design a financial strategy that is molded specifically for you. One that changes as your life changes. Financial investments to help you live worry-free now and in the future.

Advised Brokerage Accounts Are Better Diversified, Reports Schwab

Charles Schwab’s has published its' latest SDBA Indicators Report, a highly regarded, industry-leading benchmark on retirement plan participant investment activity within approximately 137,000 self-directed brokerage accounts (SDBAs).  The report stated that participants who worked with an advisor had a more diversified asset allocation mix, higher balances, and less exposure to individual stocks compared to non-advised participants.

While only 19 percent of SBDA participants chose to use an advisor, they reported an average balance of $449,552 – nearly twice as much as the $234,643 reported by non-advised participants.  SDBAs are brokerage accounts within retirement plans. These include 401Ks and other types of retirement plans, which participants can use to invest in exchange-traded funds, stocks, bonds, mutual funds and other securities that are not part of their retirement plan's core investment offerings. 

"The report highlights the benefits of working with an advisor. In general, participants who had professional help were more diversified across all of their holdings. In addition, advisors typically rebalance a portfolio more often and keep their clients invested"
-Schwab

Allocation Trends
In advised accounts, mutual funds continued to hold the highest percentage of participant assets at approximately 50 percent. ETFs were the second-largest allocation, followed by equities, cash and fixed income.

Conversely, non-advised participants allocated nearly 35 percent of their portfolio to individual equities. This was followed by mutual funds, cash, ETFs and fixed income.

When comparing equity holdings, both advised and non-advised participants held Apple, Amazon and Berkshire Hathaway as their top three holdings; however, non-advised participants’ positions in Apple and Amazon were nearly double compared to participants who used an advisor. Additionally, advised participants invested in more blue-chip, value companies, whereas self-directed investors allocated to more growth stocks.

“The report highlights the benefits of working with an advisor. In general, participants who had professional help were more diversified across all of their holdings. In addition, advisors typically rebalance a portfolio more often and keep their clients invested,” said Larry Bohrer, vice president, Corporate Brokerage Retirement Services at Charles Schwab. Generally, payroll contributions into SDBAs are allocated to cash. From there, it is up to the participant or advisor to invest. As the report shows, advisors kept clients’ cash allocations low, while individual investors left more of their SDBA in cash pending investment decisions.

Other Highlights

  • The average SDBA account balance for all participants in the third quarter of 2018 was $265,902, up 3.5 percent from the second quarter of 2018 and up 24 percent from the third quarter of 2017;
  • Advised accounts averaged 9.5 trades in the third quarter compared to 5.5 trades by non-advised participants;
  • Baby Boomers represented the majority of advised accounts (45.4%), followed by Gen X (42.2%) and Millennials (8.5%).

About the SDBA Indicators Report

The SDBA Indicators Report includes data collected from approximately 137,000 retirement plan participants who currently have balances between $5,000 and $10 million in their Schwab Personal Choice Retirement Account. Data is extracted quarterly on all accounts that are open as of quarter-end and meet the balance criteria.

6Lc_psgUAAAAAA9c7MediJBuq3wAxIyxDSt73c9j