
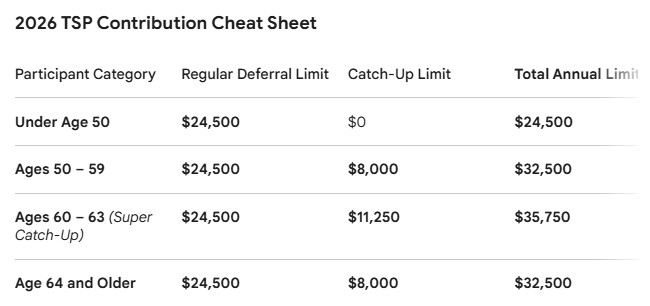
Here is a 2026 TSP Contribution Cheat Sheet designed to be easily scannable for your readers. This is a high-value resource they can save or print to ensure they are maximizing their benefits under the latest SECURE 2.0 regulations.
3 Critical Rules for 2026
- The $150k Roth Mandate: If your prior-year (2025) wages exceeded $150,000, the IRS now requires all catch-up contributions to be made to the Roth TSP. You can no longer make pre-tax catch-up contributions if you are in this high-earner bracket.
2. No More Roth RMDs: Starting in 2024 and continuing through 2026, you are no longer required to take Required Minimum Distributions (RMDs) from your Roth TSP balance while you are alive. This allows your tax-free bucket to grow indefinitely.
3. In-Plan Conversions: You now have the ability to move existing Traditional TSP balances into a Roth balance via an In-Plan Roth Conversion. This is a powerful "tax-locking" tool, but it must be handled carefully to avoid a massive tax bill in a single year.
Pro Tip: To hit the $24,500 limit exactly over 26 pay periods, set your contribution to $943 per paycheck. If you are 50+ and want to hit the full $32,500, aim for $1,250 per paycheck.