Textbook example of the single stock risk!

CAVA: Post-CMG Price Action and Market Context

CAVA shares experienced an 11% decline this morning, a notable reaction tied to the recent earnings announcement from industry peer Chipotle (CMG). This price movement reflects speculative investor sentiment, as the market appears to be extrapolating CMG's results to the broader fast-casual restaurant sector.

Single Stock Risk and Consumer Headwinds

This dramatic market reaction serves as a textbook example of single stock risk in action. When a company's stock is highly correlated with its peers, sector-wide news—even if not directly related to the company's own operations—can cause disproportionate volatility.

The immediate pain is quantifiable: CMG is down approximately 15% today and has seen its value drop 45% year-to-date. In a similar vein, CAVA is down 50% year-to-date. These significant losses underscore the severe market pessimism regarding the quick-service restaurant sector.

This volatility is further fueled by current macroeconomic trends: investors are mindful that consumers are broadly cutting back on non-essential spending, choosing to buy more groceries and eat out less. The 11% dip suggests the market is pricing in the assumption that CAVA will face similar headwinds from tighter consumer budgets when it reports on November 4th.

This is precisely why our investment process at Research Financial Strategies involves trying to mitigate this risk by focusing on Exchange-Traded Funds (ETFs) instead of individual single stocks. This approach provides immediate diversification, helping to spread the risk across a basket of companies or sectors.

We note that CAVA has not yet reported its own third-quarter earnings; the company's official results are still scheduled for release on November 4th. This stock volatility warrants close observation ahead of the confirmation (or refutation) by their actual filing.


Data Source: Yahoo Finance
Special Market Message

Dear Clients and Friends,

Are We in a Bubble?

According toThe Economist, the U.S. market may be in a giant bubble—one that could burst with a 50% drop, rivaling the Dot Com bust of 2000 and the Great Recession of 2007. You’ll see those bear markets on the attached Page Four Chart.

Bear Markets: A Pattern Worth Watching

In the past 99 years, the market has endured 22 bear attacks—defined as drops of 20% or more—roughly one every 4.7 years (source: Yardeni & Associates). But recent history has been more aggressive:

  • March 23, 2000: -34% (bear)
  • October 12, 2022: -25% (bear)
  • April 7, 2025: -18% (almost a bear)

That’s nearly three bear markets in just over five years. We’re not due for a break—we’re due for vigilance.

A Volatile Climate

Today’s political landscape may be even more charged than the early ’70s, when Nixon, Watergate, and Vietnam triggered a -48% market slide. In the past year alone:

  • Trump Assassination Attempt
  • Trump Wins
  • Doge-Doge-Doge
  • Tariffs
    Market dip (Feb 12–Apr 7)
    Rocket rebound
  • Peace in the Middle East (briefly?)
  • Ongoing: Ukraine/Russia, Government Shutdown, U.S.–China tensions, National Guard deployments

Anything Can Happen

This is not the time for autopilot investing. Headlines move markets. That’s why we actively manage your portfolio. We don’t park it in some pie-chart allocations.

At RFS, we stay alert. We monitor every ETF in our growth model (all day, every day). We track breaking news. We protect your gains.

Our Growth Model

As of 3:39 PM today, our 11 ETF positions show an unrealized gain of 16.60%. We intend to keep it that way. If you’d like a breakdown of each ETF and our rationale, reply to this email and I’ll send you the details.

For urgent questions, call my cell: 240-401-2355.

Wishing you a strong and peaceful fall,

Jack and the RFS Team

P.S.Want a preview of my new book? Chapters 1–2 are attached—readable on desktop or mobile.

Attachments:
(1) Page Four Chart JP Morgan p 4
(2) Our Aggressive Growth Model Model Account
(3) Chapters 1–2 of my new book Chapters 1 and 2 Compliments of Jack

The Fed Cut Rates: What’s in It for Me?

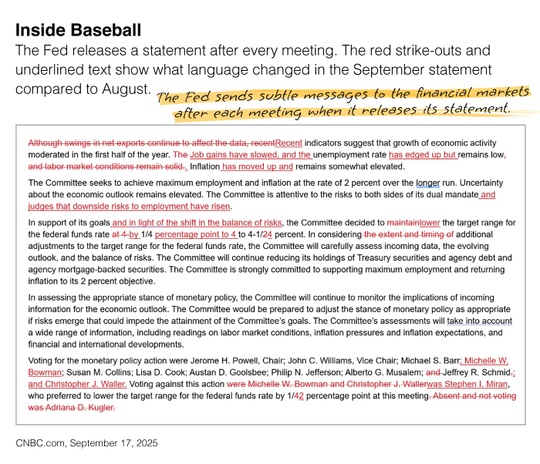
The Fed lowered short-term interest rates at its September 2025 meeting, but the question on most people’s minds is, “What’s in it for me?”

That’s a fair question, so here are some ideas to consider.

First-wave changes: Any loan considered “variable rate” can be expected to adjust relatively quickly, as with a home equity line of credit (HELOC). However, don’t get too excited. The change is likely to be relatively small.

Second-wave changes: If you’re buying a home, the Fed’s change may affect your mortgage rate. If you’re refinancing, you may also see rates change. If you’re shopping for a new car, you may see new advertised rates on car loans. 

Long-term changes: Credit card companies might adjust their interest rates, but it may take several payment cycles before you see any movement. Remember, if you have a fixed-rate mortgage, the interest rate will not change unless you refinance or sell your home.

The Fed’s September rate cut signals a shift in monetary policy by the central bank. It was the first time the Fed lowered the benchmark rate in months. Fed Chair Jerome Powell indicated more adjustments were likely this year and into 2026 to address economic concerns, including a sluggish labor market.

So, while you may see a few benefits in the short term, more opportunities may present themselves in the longer term.

If you have any questions about the Fed’s decision, please don't hesitate to reach out. I’m always happy to hear from anyone who has questions about what’s next for interest rates, especially if it involves a buying decision.

Celebrating Hardworking Americans on Labor Day

Happy Labor Day! 🛠️ 

Today, we take a moment to recognize and appreciate the hard work of individuals across the nation. 

Whether you're relaxing at home or enjoying a well-deserved day off, I hope you're able to recharge and enjoy this special day. 

To the builders, creators, and doers: Happy Labor Day!

The Shifting Landscape of U.S. Residential Real Estate

A Decline in First-Time Homeownership and a Surge in Rentals
The American housing market is experiencing a notable transformation, characterized by a significant downturn in first-time home purchases and an unprecedented expansion of the rental sector. This shift is largely attributed to a challenging environment marked by elevated borrowing costs and escalating property values, which are increasingly keeping prospective homeowners in rental accommodations.

Recent industry figures indicate a substantial reduction in the number of individuals buying their first homes. Last year, the count of new homebuyers stood at 1.1 million, a decrease of 380,000 from the previous year and nearly half of what has historically been observed. Projections for the current year suggest an even steeper decline, with sales data through May pointing to a total of approximately 40.3 million home sales across the nation. This would represent a further drop from last year's figures and the lowest sales volume recorded in the U.S. since 1995. This sales slowdown is particularly evident in the market segment for properties priced below $500,000, which traditionally attracts first-time purchasers.

The trend of diminishing new buyers is also reflected in residential construction activity. In May, new home sales saw a 6% decrease compared to the same month in the prior year. Developers often rely on demand for starter homes from first-time buyers, who historically constitute about 40% of new home sales. Consequently, a reduction in new construction suggests a corresponding decrease in the pool of new buyers seeking such properties.

As a direct outcome of these dynamics, the number of households opting for rentals has surged, reaching an all-time high of 46 million across the U.S. The financial barrier to homeownership has become considerably more formidable. Analysis from academic institutions highlights that an individual seeking to purchase a median-priced home today would require an annual income of $127,000 to manage the associated mortgage payments, a sharp increase from $79,000 just a few years prior in 2021. Alarmingly, only a fraction of the current renter population, approximately 6 million out of 46 million, meets this income threshold. This disparity is particularly pronounced among younger generations, with Gen Z and Millennials exhibiting lower homeownership rates at their current life stages compared to Baby Boomers at similar points in their lives.

Unless there are significant adjustments in mortgage interest rates or a substantial depreciation in property values—scenarios that might typically accompany an economic downturn—the aspiration of homeownership is likely to remain out of reach for a considerable segment of the American population for the foreseeable future.

Investment Ponderings from Jack Reutemann

At dinner this past week with a long-time client, I was asked what I thought of Jim Cramer.  I kindly said, “He’s a great speaker, entertainer, and educator, but I’m not sure of his investment advice track record, let me dig up the facts for you.”

An Examination of a Prominent Financial Pundit's Forecasting Record

A well-known figure in financial media appearing on CNBC’s Mad Money program, Jim Cramer who is often seen as a financial guru, frequently offers his opinions on stock market movements and specific investment opportunities. While his pronouncements often grab headlines and can immediately sway certain stock prices, a deeper look into his long-term prediction accuracy reveals a more nuanced, and often debated, picture.

In the short term, there's evidence that companies he highlights can experience an initial bump in value, sometimes seeing gains of over a percent in the hours immediately following his televised endorsements. However, this effect tends to be fleeting and does not consistently translate into superior performance over extended periods. When examining the trajectory of his recommended stocks over several months, their collective performance generally aligns with broader market indices, indicating no consistent advantage over simply holding a market-tracking fund.

Analyses of his written investment calls suggest that his success rate hovers slightly below what one might achieve through pure chance, and falls short when compared to other market strategists. A detailed review of hundreds of his "buy" and "sell" suggestions showed that while he might be correct in about three out of five immediate instances, his precision declines significantly after just a month, often leading to negative average returns. Interestingly, his advice to sell stocks sometimes fared better than his "buy" calls, though even then, his correct "sell" predictions were only accurate about 42% of the time over a longer duration.

This commentator has also been associated with several high-profile misjudgments, such as his positive outlook on a bank shortly before its collapse or repeated misinterpretations of a major cryptocurrency exchange's stock performance. These errors have fueled a popular counter-strategy, where some investors actively bet against his public recommendations, dubbing it the "Inverse" effect. Instances exist where his "sell" advice was followed by considerable gains in those very stocks, further highlighting a lack of consistent foresight.

Within investment circles, his frequent miscalls have become a running jest, inspiring even financial products designed to capitalize on taking the opposite side of his positions. His animated and dramatic presentation style is often perceived as prioritizing entertainment value over consistently sound financial guidance.

In summary, while this high-profile financial personality undeniably wields short-term influence over stock movements, his long-term ability to accurately predict market direction or consistently outperform the market remains unsubstantiated. His forecasting precision tends to be inconsistent, marked by notable misjudgments. Therefore, investors should exercise caution and avoid solely relying on his pronouncements for their long-term investment decisions.

Ultimately, for long-term financial growth, it's crucial to have a financial advisor who genuinely understands your unique situation and personal goals. Sustainable wealth building stems from a tailored strategy and disciplined approach, not from chasing risky, short-term stock plays based on televised commentary.

6Lc_psgUAAAAAA9c7MediJBuq3wAxIyxDSt73c9j